The global biopharma industry is placing increasing importance on regional support rather than only centralized expertise to help complex programs advance. A key benefit is access to local expertise in or near their time zone.
The localization movement “is part of a global shift [in which] companies are assessing how they balance cost, quality, and risks across regions rather than relying on any single market,” Jessay Devassy, PhD, global R&D director, Ecolab Life Sciences, tells GEN.
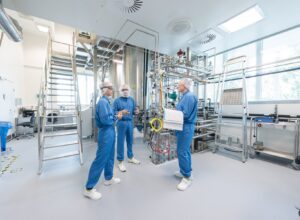
Ecolab opened a bioprocessing applications lab in Korea this spring. “Being in Korea allows the exchange of ideas in an iterative fashion…so knowledge moves seamlessly between regions. That’s much easier if you’re in their proximity,” Devassy points out.
This is the company’s first bioprocessing lab in Asia. Situated in Dongtan, Korea, it supports process development studies from early- to commercial-scale, focusing on biologics’ downstream purification.
Korea was a logical choice. “Korea is highly advanced in manufacturing,” Devassy continues. Now it’s evolving from a manufacturing hub to a comprehensive biopharma ecosystem, with active contributions from R&D all the way through clinical development, with home-grown and multinational companies alike.
With its biologics manufacturing history, “I think Korea has become one of the most trusted locations globally,” he says. “Its quality standards are well-aligned with North American and European standards.” Consequently, global clients are assured that the same approaches and standards are applied to development as in the United States or Europe.
Korea’s aspirations
Government support is part of that. The Korean government designated biopharma as a strategic industry after COVID-19 and reiterated that goal in 2023’s Third Five-year Comprehensive Plan for Development and Support for the Bio-Pharmaceutical Industry. Key points include developing two blockbuster drugs by 2027, doubling pharmaceutical exports to $16 billion, and positioning Korea among the top six nations for pharmaceutical development.
At the end of 2025:
New venture capital investments in biotech and medical companies reached $830 million, up approximately 11% from the prior year.
Total venture investments in the biotech and medical sector rose more than 29% from 2024, more than for any other industry.
Continuous bioprocessing is expected to experience a compound annual growth rate of nearly 20% between 2025 and 2030, reaching revenues exceeding $21 million.
Challenges
The competition to attract biopharma companies is robust. India is the fastest-growing Asia-Pacific market, but, Devassy says, “China has a cost advantage…[in] manufacturing and development.” It’s also the largest biopharma market in the Asia-Pacific region.
“Japan has more established domestic systems for biomanufacturing,” Devassy continues. According to Grand View Horizon, Japan leads the pack for projected revenue from continuous bioprocessing to 2030.
Devassy positions Korea “somewhere in between” China and Japan. “It’s strong technically, but is still navigating regulatory complexity and global competition.” Currently, it generates 2.2% of the world’s continuous bioprocessing revenues.
“Biopharma exports from Korea have seen strong growth recently…and Ecolab is playing a strong part in supporting the manufacturers behind that growth,” Devassy says. “This is our first step toward making our global expertise accessible to growing markets in Asia.”
Viral vector production and training schemes designed to foster development of an AI-ready workforce dominate the list of projects selected for support by the U.S. National Institute for Innovation in Manufacturing Biopharmaceuticals (NIIMBL).
The institute, a public-private partnership focused on advancing manufacturing and solving industry challenges, announced its latest funding awards, explaining that the 39 recipients would support U.S. production and talent development.
Sandeep Kedia, NIIMBL senior technology fellow and project call program lead, says the projects “represent the kind of innovation needed to strengthen the nation’s biopharmaceutical manufacturing capabilities.
“By bringing together advanced process analytical technologies, AI-driven optimization, and next-generation production platforms, our members are helping accelerate the adoption of transformative technologies across the industry,” he adds.
Several of the selected projects focus on the production of adeno-associated viral (AAV) vectors—hollow viruses used to deliver genetic information—which play a crucial role in cell and gene therapy manufacturing.
For example, researchers at Michigan Technological University will work with industry partners on an aqueous two-phase continuous vector purification system. The aim is to boost yield while reducing cost, labor, and analytical complexity.
Similarly, a team at North Carolina State aims to develop “improved purification materials that can better capture full AAVs, along with machine-learning software that identifies optimal process conditions.”
The third vector-focused project will see an MIT group work with EMD Millipore, Landmark Bio, and Virica Biotech to try to reduce the number of empty viral capsids inadvertently made during vector production.
The researchers will combine an approach called decoupled replication-initiated vector encapsulation, or DRIVE, with various process control strategies to create a platform that makes high-titer, high-quality rAAVs.
According to the MIT team, “By reducing [the proportion of] empty capsids, the approach can streamline downstream purification, reduce time and cost, and improve the overall quality of gene therapy products.”
AI-ready workforce
In addition to the technology projects, NIIMBL will support several training programs with an emphasis on ensuring the next generation of biopharmaceutical engineers are AI-ready, according to workforce director John Balchunas.
“Our workforce initiatives are designed to meet talent needs head‑on by creating more innovative pathways into biomanufacturing careers,” he says, adding, “These new projects will strengthen partnerships and ensure that learners can gain the skills needed to thrive in a rapidly evolving biopharma industry.”
One such project will see a team at Texas A&M University’s National Center for Therapeutics Manufacturing expand an existing effort called NeuroPipes, which seeks to interest neurodiverse people in careers in biopharma. The aim is to provide technical skills training that prepares neurodivergent adults for careers in drug manufacturing.
Another project will see Wistar Institute researchers set up BioPATH, a national consortium focused on advancing workforce training in biomanufacturing, AI, and automation.
The idea, according to the Wistar team and collaborators at the International Academy of Automation Engineering, is to “bridge the gap between foundational bioprocess and GMP knowledge and the emerging needs of automation, data-driven manufacturing, and digitally enabled quality systems.”
BOSTON—A critical part of the conversation around the use of artificial intelligence (AI) in drug discovery focuses on the development of the foundation models that underpin AI-based applications and workflows. There are also discussions about federated learning and how it provides a secure path to accessing critical training data for AI models. These two themes underpinned the keynote panel that kicked off the second day of Bio-IT World Conference 2026, which took place last month in Boston.
Through presentations and a group discussion, the six-person panel painted a picture of the different types of foundation models and federated learning approaches, as well as ways to optimize AI’s performance for specific projects. Importantly, they discussed the AI Structural Biology (AISB) initiative, which provides a platform for pooling proprietary protein-ligand structure data to train OpenFold3, an AI model designed to precisely predict molecular interactions. In fact, several members of the panel were either directly or indirectly involved in the OpenFold consortium.
That group included Woody Sherman, PhD, founder and chief innovation officer at PsiThera, who serves as chair of the OpenFold executive committee. Sherman reiterated the benefits of open-source platforms and how they are making inroads into the drug discovery space.
“We’re going to need these open platforms that we can all build on,” he said. “We can’t all be building our own foundation models from scratch. It just doesn’t make sense as an ecosystem. It is important to have these open platforms so that we can interact precompetitively, build the best foundation models, and then “we can get into federated learning.”
From AlphaFold to OpenFold
The non-profit OpenFold Consortium consists of scientists from over 40 technology companies, startups, pharma companies, and academic institutions. It builds on a lot of the progress made in the 2010s in terms of predicting protein structures from sequences, “a foundational problem in biochemistry.” That progress was quantified at least in part by efforts like the Critical Assessment of Structure Prediction (CAS) competitions, said Mohammed AlQuraishi, PhD, an assistant professor of systems biology at Columbia University, during his presentation.
Mohammed AlQuraishi, PhD, assistant professor, systems biology, Columbia University [Uduak Thomas]
AlphaFold and later iterations of the platform “compressed decades of progress in about four years,” he said. Besides reliably predicting protein structures, AlphaFold provided “calibrated predictions” that gave biologists a sense of the accuracy of its predictions. But there were limitations.
“It did not really have an understanding of anything other than just protein structure,” meaning it missed things like ions that were also part of the structure, he said. It also struggled to handle things like protein complexes, ligands, and cofactors. Another challenge was that although the computational models could predict targets that were closer to the training dataset used, their ability to make viable predictions dropped the further away the targets were from the training dataset. Additionally, “these models have limited ability to capture conformational changes,” AlQuraishi noted. “This becomes a major bottleneck in being able to reliably model allosteric modulators or cryptic pockets or similar types of systems.” Besides the technical limitations, there were also licensing limitations to consider.
AlQuraishi positioned OpenFold as an open source, high-performance, and reproducible alternative to AlphaFold that serves as a common platform for innovation for the community. “Partly it’s a code base, essentially a set of tools that allow [scientists] to build these types of models and extend them and apply them,” AlQuraishi explained. “It’s also an academic-industry consortium that provides a steerable mechanism for industry to support science that is open source and that’s broadly useful, but it’s also in tune with the needs of industry.”
Federated learning and foundation models
The next set of presentations made the argument for using federated learning to leverage proprietary biopharma datasets to train AI models. The presentation from Jonathan Gilbert, PhD, senior director, ecosystem growth and contributor partnerships at Eli Lilly, offered an example of how the pharma company has used federated learning to improve model predictions in different contexts.
“It’s not surprising that companies are very sensitive to the proprietary data that they’ve spent incredible investments generating,” he said. With federated learning, models are trained in the environment where the data is housed, making it possible to “improve model performance while maintaining the privacy of the individual training sets.”
Eli Lilly launched the TuneLab platform in 2025, through which it provides access to its own AI and machine learning models to biotech companies at no cost—although those that choose to use the models are expected to contribute datasets to help improve them. “These are the same models that we use every day,” he said. “These models have been trained on decades of internal data sets. That’s maybe over a billion dollars in data that have been brought into models by Lilly.”
Jonathan Gilbert, PhD, senior director, Ecosystem Growth and Contributor Partnerships, Eli Lilly and Company. [Uduak Thomas]
Gilbert noted that since its launch, the appetite for TuneLab has been quite strong. At the time of the presentation, there were more than 75 partners in TuneLab, and it was being used in dozens of countries across three continents. Furthermore, during the meeting, Eli Lilly and Collaborative Drug Discovery (CDD), a provider of data management solutions for pharma and biotech, announced an agreement to integrate TuneLab into both the core and AI modules within the CDD Vault platform.
For now, TuneLab is focused on models for small molecules and antibody development, but there are plans to release additional models in the near future. Lilly is also working on additional partnerships similar to the one with Collaborative Drug Discovery. “This is an active work in progress and [we are] thinking [about] how we can scale this,” Gilbert said. And how can “[we] build a community to improve those models such that we can create medicines faster for more people.”
The presentation from José-Tomás Prieto, PhD, director of AI programs at Apheris, built on Gilbert’s presentation but focused on the complexities of implementing industrial federated learning setups. The key takeaway from his talk was that successfully implementing federated learning at an industrial scale is not a plug-and-play capability but rather a process that requires engineering rigor, data preparation without centralization, and enterprise-level deployment strategies. His company, Apheris, has experience with this process as they provide solutions that power federated networks for drug discovery.
José-Tomás Prieto, PhD, director of AI programs, Apheris [Uduak Thomas]
One of the networks that they support is the AI Structural Biology Network, a collaboration that brings together several of the top 20 biopharma companies. Its intent is to allow AI models designed to predict the 3D structure of molecule complexes to be trained on proprietary protein structure data. The common denominator for these and other networks that Apheris supports is that the models are trained on proprietary data in a secure way, so the data never leaves the environments of any of the nodes in the network.
“It’s obvious that there’s a lot of public data, but the public data skews toward well-characterized targets,” Prieto said. “The industry data complements that view, with more diverse data and sometimes higher quality data. And if there is something to learn about the AI world today is that you cannot necessarily model your way out of a data problem, and you can’t buy this data either.” Federated learning provides a solution to that problem. “It’s quite remarkable that a couple of years ago … it was mostly IT people making the decision of whether to use federated learning products,” he noted. “Today, we have business leaders trying to get ahold of this technology and leverage the power.”
Prieto also discussed some important considerations for building federated networks. To provide a sense of the complexity involved, “each one of these companies have their own network constraints, their own firewall rules, their own compute window that they have to negotiate with the cloud providers to make sure that the compute comes online at the right time.”
It is also important to consider “that data preparation without centralization is a new paradigm,” he continued. “Each company has [their] own ways of organizing the data or harmonizing your data,” as well as their own standards, but at the same time you have to have comparable training setups so that the foundation models can actually learn from this.” Furthermore, “your federated learning partner has to be able to work with your processes, has to be able to understand how to streamline the reviews, the security [and] the privacy requirements” among other things before projects can move forward.
A key point that both Prieto and Arman Zaribafiyan, PhD, head of strategic alliances, AI simulation at SandboxAQ, emphasized was that while federated models provide broad generalizations, fine-tuning them on specific, project-level data is crucial for translating model performance into practical impact for drug programs.
SandboxAQ has worked with the OpenFold consortium on its models and co-folding models, among other projects. “We are really living in exciting times when it comes to ML-accelerated drug discovery,” Zaribafiyan said. “There’s really an explosion of new models we see every day. And what we see at Sandbox with our partners in large pharma and biotech companies is that it’s getting a little bit overwhelming and harder to put these models into good use.” Furthermore, “a lot of these models are amazing in achieving great results on benchmarks, and it’s fascinating for publishing papers, but they fail to generalize to real drug discovery use cases.”
Arman Zaribafiyan, PhD, head of strategic alliances, AI simulation, SandboxAQ [Uduak Thomas]
Commenting on some of the lessons SandboxAQ has learned through its partnerships, Zaribafiyan noted that “fine-tuning could help a lot to bridge this gap.” SandboxAQ and others have published data showing that “even a small fine-tuning effort can dramatically change the predictive accuracy of these models.” Over the next few years, he believes these are going to become the norm: “We’re going to see more and more of these federated platforms we use for both pooling data but also for fine-tuning these models on project-specific data.”
Zaribafiyan closed his presentation with an announcement of a new platform from SandboxAq that connects quantitative models for drug discovery to large language models, allowing scientists to launch and run simulations and workflows using plain English, much like prompts written for ChatGPT. “No code required,” he said.
Foundational models at work in crop science and drug development
Christina Taylor, PhD, senior science fellow and computational molecular design lead at Bayer, focused on how her company has leveraged foundational models and AI to drive decisions in crop science and pharma.
Christina Taylor, PhD, senior science fellow and computational molecular design lead, Bayer [Uduak Thomas]
“I think that this community-driven software has really allowed faster innovation in the field overall,” and “sharing some of these foundational architectures allows everyone to be able to drive biomolecular AI work,” and “ has driven some of the very quick advancements we’ve seen in the field over the past few years.” Community projects like this also save time and are more sustainable since “everybody doesn’t need to be training their own foundational models.”
To date, these models have helped Taylor and her team better solve crystal structures. “One of the big problems with solving crystal structures is actually determining the phase, and by doing protein, we’re able to actually solve these structures faster and more efficiently,” she said. “Another thing is taking these foundational models and fine-tuning them … we’re using that quite regularly to improve our development of biomolecular pharmaceuticals as well as some of our crop science traits.” Other applications that Taylor and her team have used the models for include studying protein-protein interaction as well as for modeling enzyme catalysis.
Eli Lilly has told about 50 hospitals participating in a federal drug discount program to submit comprehensive claims data over the next five days or they will no longer receive the mandated price breaks.
The move comes after the company announced a policy last January demanding such data in a bid to reduce what it calls duplicate discounts paid to participating hospitals. The issue has riled the pharmaceutical industry and contributed to a long-standing clash with hospitals over the 340B drug discount program.
For the past few years, more than 2,300 hospitals have complied with the demand, but some of the larger hospitals systems around the U.S. have refused to do so, despite recent follow-up letters regarding the policy that went into effect on Feb. 1, according to Derek Asay, senior vice president for government strategy and federal accounts at Lilly. Up to 1,000 have so far not complied.
Once labeled the “disease of kings” because of its association with consuming rich foods and alcohol, gout has emerged as a royal pain to a growing number of people. A 2024 study showed the prevalence of the most common form of inflammatory arthritis jumping 22.5% between 1990 and 2020, to 55.8 million people worldwide, with 95.8 million projected by 2050. An aging population and rising rates of metabolic conditions like obesity, hypertension, and chronic kidney disease have fueled gout’s growing prevalence.
Yet recent gout-related approvals have been limited to supplemental applications and additional indications for existing treatments. In 2022, the FDA approved an expanded label for Krystexxa® (pegloticase) by authorizing the chronic, treatment-refractory gout drug to be combined with methotrexate, a combo shown to be more effective against the disease. Last year the FDA approved Glopbera®, a new liquid formulation of colchicine indicated for prevention of gout flares in adults. The liquid formulation allows doctors to adjust dosages more easily for patients with kidney or liver impairment.
Among companies developing new gout treatments is Crystalys Therapeutics, which has dosed the first patient with its once daily oral, URAT1 inhibitor dotinurad in its Phase II AMETHYST trial (NCT07535034). The study is designed to assess dotinurad’s effectiveness in patients with gout who are intolerant or have a contraindication to xanthine oxidase inhibitors (XOIs) or have failed prior uricase treatment.
AMETHYST is expected to enroll about 90 patients, with an estimated primary completion date of July 2027. The trial’s primary endpoint will be the percentage of patients with a serum uric acid (sUA) level of <6.0 mg/dL at Week 24 following dosing.
‘Important milestone’
“Dosing the first patient in our Phase II AMETHYST study marks an important milestone for Crystalys, and for those living with gout who have limited treatment options,” said James M. Mackay, PhD, Crystalys’ president and CEO.
That population, he said, represents about 10% of gout patients or ~1.5 million Americans who cannot tolerate the current standard of care, xanthine oxidase inhibitors (XOIs). The most commonly prescribed drug for gout is the XOI allopurinol, a first-line treatment marketed in the U.S. as Zyloprim® by Casper Pharma and sold outside the U.S. as Zyloric® by Aspen Pharmacare, but also available as a generic drug.
“We think that our target population for dotinurad to is about 500,000 to 600,000 patients in the U.S.,” Mackay estimated, adding the estimate was for the broader Phase III population, not the AMETHYST Phase II population. “It’s those patients who failed allopurinol and were referred to a rheumatologist. The rheumatologist has tried to up-titrate allopurinol but has still not been successful in getting the disease under control. The patient’s still experiencing gout flares, still has tophi and potentially joint damage. That’s our target patient population.
In that class of patients, Crystalys envisions dotinurad succeeding in second-line treatment by outperforming allopurinol in their Phase III clinical trials.
“Our goal is to go beyond serum uric acid lowering and actually show that our drug can actually impact the clinical manifestations of the disease, which allopurinol really doesn’t do significantly. And as a result of that, we wanted to position it as a second-line treatment,” Mackay said. “As time goes on and rheumatologists become comfortable with it, and PCPs [primary care physicians] who are referring their gout patients to rheumatologists will get comfortable with it and we may start to see some usage in the PCP market, but I imagine that payers are going to want patients to have failed on allopurinol before they’re prepared to pay for a new drug. This is why we are positioning it as a second line treatment in patients who have failed on standard of care.”
Phase III triumph
First-patient dosing in AMETHYST comes five days after a Crystalys rival, Swedish Orphan Biovitrum (Sobi), announced positive Phase III data for pozdeutinurad, a treatment for progressive gout which like dotinurad is a next-generation, once-daily oral URAT1 inhibitor.
Sobi said May 21 that pozdeutinurad aced its pivotal 811-patient, placebo-controlled Phase III REDUCE-2 trial (NCT06439602) as both doses of the drug met the study’s primary efficacy endpoint, defined as the proportion of patients achieving an sUA level <6 mg/dL at month 6. The 75 mg high dose of pozdeutinurad led to 69.2% of patients achieving sUA level <6 mg/dL at month 6 and the 50 mg low dose, 56.6%, compared with 8.1% for placebo (p<0.0001).
Sobi said it will report further detailed results at an upcoming scientific conference during Q4.
“We are very encouraged by these results and their implications for patients whose gout remains inadequately controlled,” Lydia Abad-Franch, MD, Sobi’s head of R&D and medical affairs and chief medical officer, said in a statement. “These findings, including sustained urate lowering and a favorable efficacy and tolerability profile, support the potential of pozdeutinurad to address a significant unmet need and provide a strong foundation for regulatory submissions.”
REDUCE-2 is one of two fully recruited 12-month, 800+-patient randomized, placebo-controlled Phase III trials in which Sobi is studying pozdeutinurad. The other is REDUCE-1 (NCT06846515), which is expected to read out data in the second half of this year.
Sobi took over development of pozdeutinurad when it acquired the drug’s original developer, San Diego-based Arthrosi Therapeutics for up to $1.5 billion in a deal completed in February. Sobi agreed to pay $950 million in upfront cash plus up to $550 million cash in payments tied to achieving clinical, regulatory, and sales milestones under the companies’ acquisition deal, designed to strengthen the buyer’s gout drug franchise since pozdeutinurad is designed for patients whose treatment with first-line therapies proved unsuccessful.
“Sobi’s acquisition, we actually view that as very positive: Good for gout patients. Good that pharmas are showing an interest in this space,” Mackay said.
Sobi envisions pozdeutinurad as one of two gout drugs it aims to bring to market. The other is Nanoecapsulated Sirolimus plus Pegadricase (NASP, formerly SEL-212), a combination of the PEGylated recombinant uricase enzyme pegadricase and ImmTOR, a tolerogenic nanoparticle encapsulating the immunosuppressant sirolimus, being developed to treat uncontrolled gout. The FDA is evaluating Sobi’s biologics license application (BLA) for NASP, for which the agency has set a June 27 target action date under the Prescription Drug User Fee Act (PDUFA).
Business case
Mackay said Crystalys’ business case when it acquired dotinurad assumed that pozdeutinurad would be on the market with a similar profile: “We took a pretty conservative set of assumptions. Our market research that we did gave us a 65% market share versus 35% market share for the competitor [pozdeutinurad], and that’s with the profiles being the same.”
“We actually believe we’re going to have a better profile for the molecule, and there are a lot of patients out there,” Mackay added. “It’s a big, big market, so there’s no doubt that there’s room for more than one player here.”
How does dotinurad’s profile stand out compared with pozdeutinurad’s?
“They’re both URAT1 inhibitors, but pozdeutinurad is not quite as potent as dotinurad, so we end up using lower dose levels than they do. They were using 50 and 75 mg in their Phase III trials. We’re using 2 and 4 (mg),” Mackay said.
Mackay also cited dotinurad’s ability to target the URAT1 transporter without impacting the other transporters involved in regulating blood uric acid levels, the organic anion transporters OAT1 and OAT3, and ABCG2 (ATP-Binding Cassette Subfamily G Member 2): “We believe that that’s partially why we don’t have a renal tox liability, because it means that there’s more control over the excretion of the uric acid.”
“This is a very, very big second-line space here. There are many, many patients who are uncontrolled, and so, we made the assumption that pozdeutinurad would be on the market alongside dotinurad.”
To date, Sobi has the advantage of positive Phase III data showing reduced serum uric acid, with expectations for more positive data this year: “Later we will see the tophi reduction, the tophi resolution and the flare reduction. We’re expecting very strong data,” Lydia Abad-Franch, MD, MBA , Sobi’s head of R&D and chief medical officer, told analysts April 28 on the company’s Q1 earnings call.
At its Capital Markets Day on February 18, Sobi told analysts that upon approval, followed by a launch scheduled for 2028, pozdeutinurad is expected to generate blockbuster-level peak sales of SEK 10 billion ($1.075 billion) from a progressive gout patient population it has pegged at more than 200,000 patients in the U.S. alone. “Pozdeutinurad represents the primary economic opportunity for Sobi in our gout franchise,” Guido Oelkers, Sobi’s president and CEO, said at the event.
Long-term sales generator
In announcing Sobi’s acquisition of Arthrosi in December, Oelkers said the company sees pozdeutinurad as a long-term sales generator: “The product has the potential to materially accelerate our growth until the mid-2030s, and beyond.”
AMETHYST is among randomized, double-blind, multicenter trials Crystalys is conducting in the U.S. and European Union (E.U.) for dotinurad. Two of the trials are in Phase III, both aiming to evaluate dotinurad’s efficacy in lowering sUA at week 24:
RUBY (NCT07089875), a U.S. and E.U. study evaluating the safety and efficacy of dotinurad compared with a physician-determined stable dose of allopurinol in approximately 500 patients with hyperuricemia associated with gout. Study participants will be given dotinurad orally once daily for up to 64 weeks.
TOPAZ (NCT07089888), a U.S. study assessing the safety and efficacy of dotinurad compared to allopurinol in approximately 250 patients with tophaceous gout. Participants are being given dotinurad orally once daily for up to 76 weeks.
Crystalys acquired dotinurad in 2024 by purchasing from Urica Therapeutics its license covering development and commercialization rights in the U.S. as well as Europe, the Middle East, and North Africa, from the drug’s discoverer, Japanese pharma Fuji Yakuhin. In return, Crystalys gave Urica—a subsidiary of Fortress Biotech—an equity stake in Crystalys and a 3% royalty on future net sales of dotinurad.
In Asia, Fuji Yakuhin has licensed to Eisai rights to dotinurad, which is approved as a treatment for gout and hyperuricemia in China, Japan, Thailand, and the Philippines.
25+ novel gout drugs
As of September, more than 20 companies had developed over 25 novel drugs across various clinical stages for indications related to gout, according to DelveInsight. Among later phase drugs in clinical phases with gout indications:
Dapansutrile (OLT1177®)—Olatec Therapeutics’ oral NLRP3 inhibitor is under study in the Phase II/III PODAGRA II trial (NCT04971499) in roughly 300 patients with an acute gout flare. The study’s estimated completion date is December 31. In March, Olatec began studying dapansutrile in the Phase II DAPA-PD trial, a 12-month study of the drug as a treatment for Parkinson’s disease.
Epaminurad—JW Pharmaceutical said April 27 that it finished dosing the final patient in a Phase III trial (NCT05815901) designed to compare the safety and efficacy of the selective URAT1 inhibitor to febuxostat, which in the U.S. is a generic drug once marketed by Takeda Pharmaceutical as Uloric®.
Lingdolinurad (ABP-671)—Atom Therapeutics’ lead candidate, also a selective URAT1 inhibitor, is in Phase IIb/III trials worldwide, including the U.S., for indications that include chronic gout and hyperuricemia, and refractory and/or tophaceous gout. Last October at the American College of Rheumatology’s ACR Convergence 2025, Atom presented positive Phase IIa data for lingdolinurad and Phase I data for a separate gout flares candidate, ABP-745.
XRx-026—XORTX Therapeutics’ Phase III gout candidate uses a proprietary formulation of oxypurinol, the active subunit of allopurinol, called XORLO. XRx-026 is being developed for patients with allopurinol intolerant gout.
Mackay, a veteran pharmaceutical executive, was a 30-year AstraZeneca executive who held several VP-level clinical and product positions with the pharma giant, where he led teams that advanced six drugs through development and commercialization across a range of therapy areas. He later oversaw development of AstraZeneca’s gout franchise as president and COO and then CEO of Ardea Biosciences, which remained an independent business unit following its acquisition in 2012 by AstraZeneca.
In 2018, Mackay founded Aristea Therapeutics, an immunology focused company developing treatments for rare inflammatory disorders. As Aristea’s CEO, he led the company’s raising of $138 million between 2018 and 2023.
That year, Mackay said, Aristea discovered an unexpected liver toxicity issue during Phase II trials of its lead drug RIST4721, which it licensed from AstraZeneca. RIST4721 was an antagonist of the CXCR2 protein that was being studied as a treatment for the inflammatory disorder palmoplantar pustulosis. Aristea’s board considered strategic alternatives before opting to end the RIST4721 development program—”in order to protect patient safety,” the company stated at the time—and dissolve Aristea.
‘Want to work with you’
“Once the dust had settled a little bit, my main investor in Aristea Therapeutics came back to me and said, look, we want to work with you and the team again,” Mackay recalled.
The investor was Novo Holdings, the asset manager of the foundation that controls Novo Nordisk.
“They said, ‘We’re really interested in the gout space and would like to invest there,’” Mackay recalled. “Are you prepared to work with us and see if we can find an asset that, is worthy of developing and worthy of investment?”
Mackay agreed.
“We did a landscape search of all the molecules under development, and we identified dotinurad as the molecule that we felt had best-in-class safety and efficacy, and we decided to form Crystalys Therapeutics with Catalys Pacific and Novo Ventures as the company to, basically, develop dotinurad,” Mackay added.
Novo Holdings and Catalys Pacific joined SR-One in launching Crystalys last September with a $205 million Series A that also saw participation from an investor syndicate that included Perceptive Xontogeny Venture Funds, Lightstone Ventures, AN Venture Partners, funds managed by abrdn Inc., KB Investments, Pontifax, Longwood Fund, Alexandria Venture Investments, Wedbush Healthcare Partners, and Prebys Ventures Fund.
The financing extended Crystalys’ financial runway into end 2027—long enough, the company says, to allow it to carry out both the RUBY and TOPAZ trials: “We secured all the money that we need in order to deliver those programs,” Mackay said.
Based in San Diego, Crystalys has a workforce of 14 staffers: “I expect we’ll probably double the size, so around 25 people by the time we get into the end of 2026.”
Workforce growth will primarily take place in Crystalys’ R&D operations since the company’s focus will continue to be on its clinical trials—not only AMETHYST but the Phase III RUBY and TOPAZ studies as well.
“I think it’ll be into 2027 before we start to build that commercial infrastructure,” Mackay added.
The 2030 patent cliff may either decimate revenue streams or provide an opportunity for innovation that can transform the biopharmaceutical industry. As it stands today, some 200 biopharmaceuticals are scheduled to go off patent during the next four years, representing approximately $300 billion in revenue.
That revenue hit can be softened if biopharma manufacturers replace traditional mammalian expression systems with a Lemna plant-based system. Susan Stipa, CEO and co-founder of Phylloceuticals, tells GEN the Lemna platform her team has developed can reduce operational costs by nearly 80%–90% per gram in the upstream part of the process and one-third the cost overall. That’s because Lemna-based production lacks the 12-month lag and need for sterile growth media associated with mammalian cell lines and has less need for viral deactivation.
Demonstrating those points, Phylloceuticals’ Lemna-based approach produced microgram quantities of the PD-1 inhibitor pembrolizumab in only 16 weeks. Batch harvesting garnered “yields of approximately 0.6 grams purified mAb per kilogram of fresh weight,” Stipa says.
This isn’t how production has been traditionally handled, she says. So, “most companies are making defensive plays—such as mergers and acquisitions, reformulations, and reducing headcounts. But…what if the patent cliff could be an opportunity?”
The duckweed advantage
In optimal conditions Lemna, a genus of small free-floating aquatic flowering plants also known as duckweed, can double within 36 hours. In the wild, five to seven days is normal. “It’s one of the most prolific plants in the world,” Stipa points out. That rapid doubling time creates a huge speed advantage for line development and scale-up. “Line development speed for Lemna is four to six months versus 18+ months for Chinese hamster ovaries (CHO) cells,” Stipa says, “primarily due to Lemna’s genetic stability and clonal growth.” It boasts inexpensive, animal serum-free growth medium, no adventitious viruses, a negative carbon footprint, and uses about 10% of the water used by CHO cell systems to produce mAbs. And, she adds, “There is near-zero impact from unforeseen environmental deviations, like power outages.”
Susan Stipa CEO, Co-Founder
Importantly, “As a multicellular eukaryote, it possesses the advanced chaperones and complex post-translational modification machinery—specifically sophisticated N-glycosylation—required to correctly fold and stabilize large, bioactive human molecules. Our ability with duckweed to control sugars and, in particular, obtain human (or human-like) sugar profiles is what sets us apart.”
Those features make Lemna an attractive alternative to the more expensive CHO and other mammalian cell lines. CHO cells require a very complex system, and “thousands of CHO cells must be screened to find the cell that produces the right protein and remains genetically stable. There can be genetic drift, but with Lemna, there is none,” Stipa points out. Mammalian cells are sensitive to environmental fluctuations and require skilled technicians to manage them.
“Almost anything you can make in mammalian cells, you can make in duckweed, just a little bit better. And, yes, we do a bit better with folding,” she says.
Yeast such as Pichia pastoris or Saccharomyces cerevisiae is another option, but Stipa points out, “Yeast is a story of quantity versus quality. It can produce a lot very quickly, and it does simple proteins very well, but when the protein size and complexity increase, productivity drops.”
Building where there’s a need
That said, Phylloceuticalshas a potentially broad client base that includes individual investigators needing microgram quantities up to contract development organizations, biosimilar manufacturers, and innovators. The company is still young, though. “We need to prove the platform is what the industry wants it to be,” Stipa says.
Stipa developed a comprehensive view of the industry as a young cancer patient and through a career as a chemical process engineer who built biopharma facilities globally, and as a life sciences marketer exposed to many companies.
Her time in marketing, in fact, led to the formation of Phylloceuticals. “I had developed brand strategy for so many start-ups only to see the scientist-founders lose the room pretty quickly,” Stipa says. “In today’s media-saturated world, innovative science also needs advocates able to tell incredibly compelling stories, and to tell them so they stick.”
In 2024, Stipa and her co-founders, Lynn Dickey, PhD, now chief technology and science officer, and Bill Brydges, one of the original leaders of bioengineering firm Foster-Wheeler Biokinetics, incorporated Phylloceuticals.
The company became operational in January 2025, opening its pilot facility in Rapid City, South Dakota. “Our location choice perfectly mirrors the bio-agility of our platform,” Stipa says. “Traditional mammalian cell [production facilities] are often tied to very specific legacy pharma hubs. The idea of Phylloceuticals is that we can be up and running anywhere the need is, and in underserved regions. Rapid City is at the core of one of the largest rural healthcare areas [in the U.S.].”
That the facility was operational in only 12 weeks helped Phylloceuticals transition from friends and family financing to angel investment. Stipa says she expects to close the company’s first funding round soon, “to be followed immediately by a Series A round.”
Initial focus: biosimilars
The company’s focus on biosimilars is directly related to the patent cliff and the industry’s widely discussed onshoring. The COVID pandemic highlighted a flaw in the global supply chain that left nations dependent upon others for critical pharmaceutical ingredients. Plugging that gap with the Biosecure Act (signed into law December 2025) and Federal Acquisition Regulations that ban commerce with companies of concern, Stipa says, makes Phylloceuticals an attractive choice for low-cost, onshore, mAb production. “Beyond biosimilars, we are also very active in animal health biologics and ADC/RTL support,” she adds.
Regulators—notably the FDA—are familiar with Lemna because of its commercial-scale use for food, and for pharmaceutical products that have been through Phase II, including β-interferon, although it hasn’t been used commercially for pharmaceutical products. Commercial scale has been on Stipa’s mind since the beginning. “From the very early months, we had a team beginning to think about what scale-up would look like. Even when we didn’t have the funds, we had advisors working on the scaleup question,” Stipa says. Currently, Phylloceuticals can make microgram-to-gram quantities. Its next phase is to make gram-to-kilogram quantities.
Challenges
“I think pharma rarely fails because of the science,” Stipa says. She says the company is still improving extraction from the apoplast (the network of cell walls and intercellular spaces that help transport water and nutrients) and scaling to commercial quantities.
Instead, the big challenge for Phylloceuticals is simply innovating in an industry that has a legacy, multi-billion-dollar investment in stainless steel infrastructure. “Change is hard,” she acknowledges. But change is also inevitable, and the biopharmaceutical industry is hardly the first to face entrenched legacy equipment and processes.
As an example, she cites Kodak, which invented the first digital camera in 1975 but didn’t commercialize it. Aside from its initial technical immaturity, digital photography “would challenge the paradigm of film and chemicals Kodak sold,” Stipa points out. Yet, today, more than 90% of all photos are digital, and film photography is a relatively small niche. Clearly, she says, “It is possible to shift a legacy mindset.
“Our challenge is to find forward-thinking leaders who believe the same way [we do],” Stipa continues. The first two customers have signed on—one engaged in preclinical studies around joint disease, and one focused on animal health—which suggests such leaders are there and are open to new ways of doing things.
“The industry is at a crossroads,” Stipa says. “I see this as an opportunity to help our partners transition from ‘how we’ve always done it’ to a model of bio-agility.”
Phylloceuticals
Location: 800 N. King Street, Suite 304, Wilmington, DE 19801
Focus: Phylloceuticals has developed a plant-based expression system using Lemna (duckweed) as the bioreactor that has produced a mAb in 16 weeks, start to finish. As a multicell eukaryote, Lemna has the cellular machinery necessary to correctly fold and stabilize large, bioactive human molecules.
Some of the forces that shape biopharma cluster development are constants year after year, such as the emergence of startups from university and research institute labs to develop new treatments, thanks to ideas backed by the brains of researchers and executives, and the bucks of serial entrepreneurs and other investors.
But in recent years, several additional unique circumstances have come to reshape how much and especially where biopharmas choose to grow, Matthew Gardner, CBRE Americas Life Sciences Leader, shared with GEN recently.
One is increased acquisition of lab and manufacturing properties by “mid-cap” biopharmas ranging between $2 billion and $10 billion in market capitalization (share price times the number of outstanding shares), as they seek to better control their supply chains by maintaining their own infrastructure in evolving from research- to commercialization-focused drug developers.
“They might have been more likely to lease in a different circumstance. They’ve definitely caught an opportunity to jump in and take ownership. That has been an ongoing trend, and that has been true coast-to-coast in most of the major centers,” Gardner said.
Among investor-owners, Gardner said, another transition has begun from pure-play biopharma real estate landlords to investors with broader portfolios encompassing healthcare—a reflection of how the two fields are increasingly converging. During December 2025 and January 2026, for example, the public real estate investment trust (REIT) Healthpeak shelled out $600 million to close on the acquisition of a 1.4-million square foot, 29-acre campus on Gateway Boulevard in South San Francisco, CA, from the nation’s largest biopharma REIT, Alexandria Real Estate Equities and BXP (formerly Boston Properties).
Those and other investors aim to cash in on the improving climate for biopharmas seeking to raise capital, from a recovering venture capital market to increased merger-and-acquisition (M&A) activity, and, in recent weeks, a revived market for initial public offerings (IPO).
Another key factor in recent cluster-building cited by Gardner is the “reshoring” of manufacturing in the U.S. by global biopharma giants, whether to satisfy growing demand for treatments—especially obesity drugs—or avoid tariffs, or both. While many of those new facilities are in manufacturing-heavy clusters like North Carolina and Greater Philadelphia, others have spread into Maryland and Virginia (the BioHealth Capital Region), and several new biomanufacturing sites have been built or are under construction in emerging clusters outside the Top 10—a trend GEN plans to explore in the coming weeks.
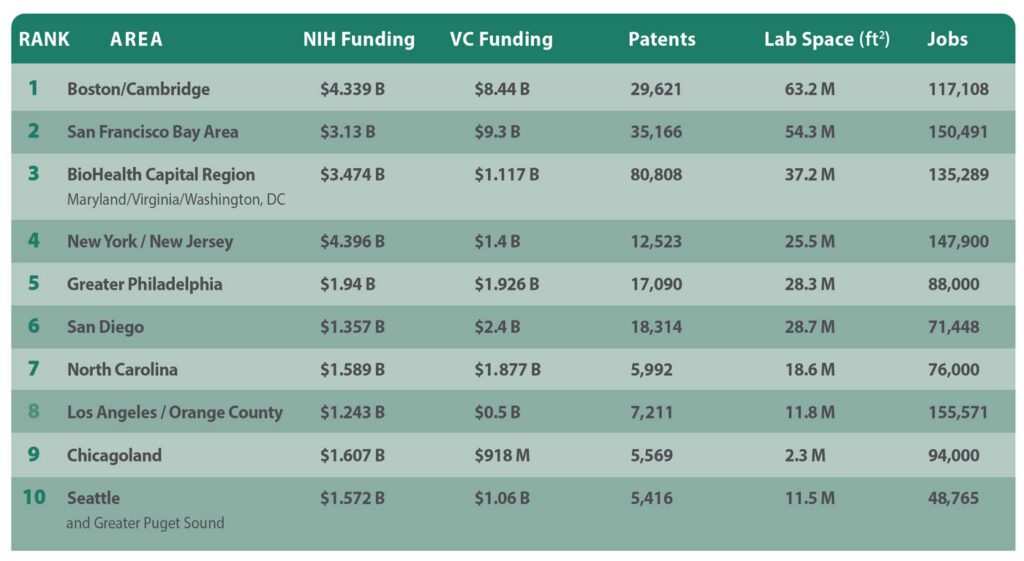
Speaking of top 10 clusters, GEN presents its latest edition of its nationally- and regionally-cited annual A-List of its top 10 U.S. biopharma cluster rankings, designed to show which regions are most competitive in attracting life sciences leaders, companies, and institutions. Over more than a decade, GEN has based its rankings on five criteria:
Patents: Figures from the Patent Public Search database of the U.S. Patent and Trademark Office, showing the number of patent families containing the word “biotechnology” and towns and cities within a given region or state.
NIH funding: Figures for NIH funding were taken from the publicly available NIH Research Portfolio Online Reporting Tools (RePORT) database for the current federal fiscal year through May 4, plus all of fiscal year 2025 (October 1, 2024, through September 30, 2025).
Venture capital funding: Figures for all of 2025 and the first quarter of 2026 as compiled by regional life sciences groups and PitchBook, which joins with the National Venture Capital Association to publish the quarterly Venture Monitor reports.
Laboratory space: The total-size-of-market figure, in millions of square feet, as furnished by regional life sciences groups. In regions that did not compile such information, the figure cited is the highest by any of several commercial real estate companies, including CBRE Group, Colliers, Cushman & Wakefield, JLL, and Newmark.
Number of jobs: The preferred sources for job figures were regional life sciences groups. Alternative sources included commercial real estate firms.
1. Boston/Cambridge, MA
Genentech has agreed to more than triple its space, growing from 30,000 to 100,000 square feet, within 1 Milestone Street at the Harvard University-owned, Tishman Speyer-developed Enterprise Research Campus in Boston’s Allston section [Breakthrough Properties, Studio Gang & Henning Larsen]
Years of growing into the nation’s top biopharma cluster have taken a toll on Boston and adjacent Cambridge, MA: The Wall Street Journal in December highlighted the inability of Boston-area PhDs to find work, while the region faces a glut of life sciences space as biopharmas and real estate developers scale back earlier plans—a 32.7% availability rate according to CBRE, up 70 basis points from Q1 2025. Takeda Pharmaceutical in March eliminated 247 jobs in Massachusetts, where the company has facilities in Lexington, MA, and Cambridge, part of a $1.3 billion restructuring that cut 634 jobs nationwide. Replimune in April chopped 223 jobs at its Woburn, MA, HQ, and Framingham, MA, manufacturing site after the FDA rejected its BLA seeking approval for RP1 [plus Bristol Myers Squibb’s Opdivo® (nivolumab)] for advanced melanoma. In February, Takeda placed 449,140 square feet within three Cambridge buildings on the sublease market, a week after Alexandria Real Estate Equities scrapped plans to convert 401 Park Drive in Boston’s Fenway section into lab space, with CEO and chief investment officer Peter M. Moglia saying the real estate investment trust was pivoting to meet growing demand for office space.
Among the region’s growing life-science companies: Genentech agreed to more than triple its space, growing from 30,000 to 100,000 square feet within One Milestone Street at the Harvard University-owned, Tishman Speyer-developed Enterprise Research Campus in Boston’s Allston section. Hemab Therapeutics (based in Cambridge and Copenhagen) and Seaport Therapeutics (Boston) both priced IPOs on April 30, raising $301.5 million and $254.88 million, respectively—a day after Avalyn Pharma (Boston) garnered $300 million in its IPO. In March, Terrestrial Bio became the first life-science tenant at Allston Labworks (250 Western Avenue) by leasing 42,000 square feet at the mixed-use building within Boston’s Allston neighborhood, while AI Proteins in January inked a 40,000-square-foot lease at 660 Commonwealth Avenue, within Related Beal’s One Kenmore Square in Boston. Regional companies finding buyers in April include Boston-based Kelonia Therapeutics and Cambridge-based Ajax Therapeutics, both to be acquired by Eli Lilly (for up to $7 billion and up to $2.3 billion, respectively) and Framingham-based KalVista Pharmaceuticals, to be acquired by Italy’s Chiesi Group for about $1.9 billion.
Boston/Cambridge enjoys the nation’s largest portfolio of lab space (63.2 million square feet according to industry group MassBio), but was bested by the San Francisco Bay Area in NIH funding (7,037 awards totaling $4.339 billion) following a year of government funding cuts. The region also placed second in VC ($6.85 billion in 2025, says MassBio; $1.59 billion in Q1 2026, according to PitchBook data cited by MassBio), but landed third in patents (29,621 families) and just fifth in jobs (117,108, according to MassBio).
2. San Francisco Bay Area
Eli Lilly Chair and CEO David A. Ricks and Nvidia Founder, president, and CEO Jensen Huang announce the companies’ five-year, $1 billion partnership to create a “Co-Innovation AI Lab” designed to address key challenges in AI drug discovery, announced on January 12 during the J.P. Morgan 44th Annual Healthcare Conference in San Francisco. The lab will be located within the Bay Area. [Nvidia]
Santa Clara, CA-based Nvidia and Eli Lilly electrified the annual J.P. Morgan Healthcare Conference, held in downtown San Francisco each January, by announcing a five-year, $1-billion collaboration to create a “Co-Innovation AI Lab” in the region to address key challenges in artificial intelligence (AI) drug discovery, powered by a supercomputer that went live in February. That welcome news aside, more than one-third of the region’s life-science space is available for lease (33.7% as of Q1, according to CBRE). And more space has entered the market: Pfizer confirmed plans in April to shut down its 164,000-square-foot research facility at 181 Oyster Point Blvd. in South San Francisco, CA, shifting employees to remote jobs. Cushman & Wakefield is marketing the space for sublease. Also, on the market in “South City” is a 21,552-square-foot lab building and surrounding 3.65 acres previously occupied by the U.S. Department of Agriculture, which is selling the building for just under $48 million. In May, Foster City, CA-based Gilead Sciences disclosed plans to lay off 108 employees based in Redwood City, CA, (and 84 in Rockville, MD) following its $7.8-billion acquisition of Arcellx.
Not all the recent news is bad: Gladstone Institutes plans early next year to open approximately 20 new labs employing about 300 scientists within the 105,000 square feet it agreed to lease in March at 1450 Owens Street, within Alexandria Real Estate Equities’ Alexandria Center® for Science and Technology–Mission Bay Megacampus. Natera inked a 62,969-square-foot lease at Brittan West in San Carlos, CA, in February. And last fall, Elon Musk’s Neuralink leased the entire approximately 144,000-square-foot 499 Forbes Boulevard in South San Francisco. On the financing side, SF-based Breakout Ventures in March closed its $114-million Fund III, which aims to invest in founder-led companies applying AI in biopharma, while Palo Alto, CA-based Surf Bio, whose lead investor for its only institutional round was Breakout, was acquired by San Diego-based Halozyme Therapeutics for up to $400 million, in a deal announced in January.
San Francisco and its suburbs topped Boston/Cambridge in VC ($7.8 billion in 2025, $1.5 billion in Q1 2026, both according to PitchBook). The Bay Area is second in three criteria: patents (35,166 families), lab space (54.3 million square feet according to Colliers), and jobs (150,491 according to BIOCOM California, but “more than 147,000” according to CBRE, both from last year). In NIH funding, the region is fourth (5,180 awards totaling $3.13 billion).
3. BioHealth Capital Region (Maryland, Virginia, and Washington, D.C.)
AstraZeneca has expanded the scope of its new manufacturing facility in Rivanna Futures, near Charlottesville, VA, into a $4.5 billion project designed to support manufacturing for weight management, metabolic, and cancer technologies, including antibody-drug conjugates. The project is expected to create 600 permanent jobs. [AstraZeneca]
The BHCR takes in Virginia and Maryland, both of which benefited over the past year from the domestic “reshoring” of biomanufacturing by pharma giants. AstraZeneca in November announced $2 billion in plans for Maryland that include a major expansion of its biologics manufacturing facility in Frederick, MD, and a new clinical manufacturing facility in Gaithersburg, MD. A month earlier, AstraZeneca expanded the scope of its new manufacturing facility in Rivanna Futures, near Charlottesville, VA, into a $4.5-billion project designed to support manufacturing for weight management, metabolic, and cancer technologies, including antibody-drug conjugates. The project is expected to create 600 permanent jobs. Also last fall, Merck & Co. broke ground on a $3 billion, 400,000-square-foot Center of Excellence for Pharmaceutical Manufacturing at its longstanding site in Elkton, VA, while Eli Lilly announced plans for a $5-billion manufacturing facility just west of Richmond, VA, in Goochland County that will be the company’s first-ever dedicated, fully integrated active pharmaceutical ingredient (API) and drug product facility for its bioconjugate platform and monoclonal antibody portfolio. However, a longtime strength of the region—the headquarters presence of the NIH and FDA—is now among its most serious challenges as government funding cuts chopped the workforces of both agencies last year by 3,500 and 1,200 jobs, respectively, though the FDA in recent months has worked to hire 1,000+ new staffers to fill reviewer, inspector, and investigator roles. And in May, Gilead Sciences disclosed plans to lay off 84 employees in Rockville, MD (and 108 in Redwood City, CA) following its $7.8-billion acquisition of Arcellx.
The BioHealth Capital Region fulfills its top-three cluster ambitions by continuing to lead the nation in patents (80,808 families) while placing third in NIH funding (4,665 awards totaling $3.474 billion) and lab space (37.208 million square feet according to JLL data cited by BHCR, including 9.2 million square feet of NIH labs in Bethesda, MD). The region is fourth in jobs (135,298, according to JLL and state data cited by BHCR), but seventh in venture capital ($1.117 billion in 2025, zero in Q1 2026, according to BHCR data).
4. New York/New Jersey
In New Jersey, New Brunswick’s Planning Board in February approved the $468 million H-3, the third phase of the HELIX downtown campus, a 40-story 554,000 square foot tower, for which the city council approved a 30-year PILOT agreement that will generate $1.8 million a year in annual payments in lieu of taxes [DEVCO New Brunswick Development Corp.]
The Big Apple will soon see a big biotech campus emerge, the $1.6 billion, 2-million-plus-square-foot Science Park and Research Campus (SPARC) Kips Bay, projected to create more than 15,000 jobs by combining life-science space with academic and public health facilities. Exterior demolition is scheduled for the third quarter, followed by construction next year. However, Johnson & Johnson has shifted operations of its JLABS@NYC incubator to site owner New York Genome Center, part of a corporate cutback of its incubator network. The 17-member Emerging Technology Advisory Board appointed by New York Gov. Kathy Hochul (D), who is seeking re-election this year, proposed numerous efforts in December to expand life sciences activity statewide, including a $65-million “Excellence” fund and a $40-million pre-commercialization fund. At deadline, the fate of those efforts was unknown despite a tentative agreement on May 7 of a $268-billion state budget.
In New Jersey, New Brunswick’s Planning Board in February approved the $468-million H-3, the third phase of the HELIX downtown campus, a 40-story, 554,000-square-foot tower, for which the city council approved a 30-year PILOT agreement that will generate $1.8 million a year in annual payments in lieu of taxes. In suburban Westchester County, Regeneron Pharmaceuticals is completing a $1.8-billion HQ expansion in Tarrytown but has scuttled earlier plans to expand across the Hudson River into the Rockland County village of Suffern, where the company spent $39 million to buy an old Avon Cosmetics warehouse for conversion into an infectious disease lab and a cold storage facility. In February, Regeneron hired JLL to market the site for sublease.
New York and its northern New Jersey suburbs lead the nation in NIH funding (7,033 awards totaling $4.396 billion) and are third in jobs (147,900, according to Cushman & Wakefield). From there, the region falls to the middle of the pack, placing fifth in VC ($1 billion in 2025 and about $400 million in Q1 2026, both according to PitchBook), and sixth in both lab space (25.5 million square feet, according to Colliers) and patents (12,523 families).
5. Greater Philadelphia
Eli Lilly made history in January by announcing Pennsylvania’s largest-ever biotech project, a $3.5 billion biomanufacturing site planned for Upper Macungie Township, an hour’s drive northwest of Philadelphia. Lilly plans to base 850 jobs at the plant, which will produce retatrutide and other weight loss drugs when it becomes operational in 2031. Lilly also has plans for Philadelphia, namely a 44,000-square-foot Lilly Gateway Labs innovation hub in Center City West at 2300 Market set to open later this year. [Eli Lilly]
Eli Lilly made history in January by announcing Pennsylvania’s largest-ever biotech project, a $3.5-billion biomanufacturing site planned for Upper Macungie Township, an hour’s drive northwest of Philadelphia. Lilly plans to base 850 jobs at the plant, which will produce retatrutide and other weight loss drugs when it becomes operational in 2031. Lilly also has plans for the City of Brotherly Love, namely a 44,000-square-foot Lilly Gateway Labs innovation hub in Center City West at 2300 Market set to open later this year. And, in Philadelphia’s Old City, Thermo Fisher Scientific last November opened its East Coast Advanced Therapies Collaboration Center (ATxCC) within the BioLabs for Advanced Therapeutics incubator.
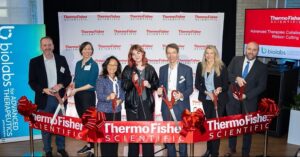
Thermo Fisher Scientific executives last November celebrated the opening of the biotech tools giant’s East Coast Advanced Therapies Collaboration Center (ATxCC) in Philadelphia’s Old City, within the BioLabs for Advanced Therapeutics incubator. [Thermo Fisher Scientific]
The region’s rich biotech history includes the first gene therapy Luxturna® marketed by Roche-owned Spark Therapeutics—which is completing its $575 million Gene Therapy Innovation Center in University City despite laying off more than half of its Philly staff last year. In March, TerraPower Isotopes announced plans for a $450-million radioisotope manufacturing facility designed to produce actinium-225 for cancer treatments. The project will employ 225, receive $10 million in state grants, and rise within The Bellwether District, the 1,300-acre former Philadelphia Energy Solutions refinery site. Greater Philadelphia has long benefited from innovations from its institutions, two of which won more than $100 million in NIH funding during the 2025 federal fiscal year, the Perelman School of Medicine at the University of Pennsylvania to Children’s Hospital of Philadelphia (CHOP)—which last year treated KJ Muldoon (“Baby KJ”), the world’s first patient to receive a personalized CRISPR gene-editing therapy (for CPS1 deficiency). The region’s needs for more C-suite talent and venture capital remain persistent challenges to cluster growth, stakeholders told The Philadelphia Inquirer in December, though Audrey Greenberg, chair of corporate development and “Mayo Venture Partner” at Mayo Clinic and founder of AG Capital Advisors, told the Inquirer: “I’m going to be starting my companies all here in Philadelphia, because that’s where I am.”
Greater Philadelphia improved the most this year, climbing two positions in this year’s A-List after remaining fifth in patents (17,090 families) and rising to fifth in lab space (25.9 million square feet, according to Colliers’ data cited by Pennsylvania’s Department of Economic Development or DECD) and NIH funding (3,201 awards totaling $1.94 billion). The region jumped four spots to fifth in VC ($1.31 billion in 2025, $616 million in Q1 2026, says Colliers), but dipped to seventh in jobs (88,000, also according to DECD), including nearly 10,000 with cell and gene therapy expertise.
6. San Diego
Novartis broke ground in February on a $1.1 billion, 466,000-square-foot global Biomedical Research center in San Diego, expected to house 1,000 employees when operational in 2029, three months after opening a radioligand therapy manufacturing facility for cancer treatments in Carlsbad, CA. [Novartis]
The Biotechnology Innovation Organization (BIO) expects to draw 20,000 to its BIO International Convention when it returns this month to the San Diego Convention Center. The region remains a vibrant life-sciences cluster: Novartis broke ground in February on a $1.1-billion, 466,000-square-foot global Biomedical Research center in San Diego, expected to house 1,000 employees when operational in 2029, three months after opening a radioligand therapy manufacturing facility for cancer treatments in Carlsbad, CA. Eli Lilly in March completed its $1.2-billion acquisition of home-grown Ventyx Biosciences—months after the pharma opened a Lilly Gateway Labs innovation hub with Alexandria Real Estate Equities in Torrey Pines. The J. Craig Venter Institute—whose founder died April 29 at age 79—plans this summer to move its West Coast headquarters from the University of California San Diego campus in La Jolla to the downtown Research and Development District (RaDD), a $1.6-billion, 1.7-million-square-foot campus on the city’s Pacific coastline completed last year by San Diego-based developer IQHQ—which is fighting an investor’s fraud allegations related to a $50-million investment in 2020. Home-grown F5 Therapeutics (up to 10 employees) folded in March, while two other San Diego biotechs laid off employees this year: Gossamer Bio (65 employees, nearly half its workforce, as of May 15, following a Phase III trial failure) and BioAlta (70% of its staff, which was 41 as of December 31, 2025). In February, San Diego drug developer Iambic Therapeutics inked an up-to-$1.7-billion collaboration with Takeda Pharmaceutical, which will use Iambic’s AI technologies and wet lab capabilities to design and develop small molecule drugs. And global contract development and manufacturing organization (CDMO) Bora Biologics, in January, opened a $30-million expanded manufacturing facility with two to four 2,000-liter bioreactors, corresponding seed trains, and advanced downstream processing equipment.
“America’s Finest City” and vicinity stayed third in VC ($1.9 billion in 2025, says PitchBook, $743 million in Q1 2026 according to a GEN spot-check of recent deals) and fourth in patents (18,314 families) but dipped to fifth in lab space (28.685 million square feet, according to CBRE). While the San Diego region last year rose to ninth in NIH funding (2,001 awards totaling $1.357 billion), it slid to ninth in jobs (71,448, according to year-old BIOCOM California data).
7. North Carolina
Roche’s Genentech subsidiary in January expanded to $2 billion its planned investment in its first East Coast manufacturing facility in Holly Springs, NC, which broke ground last year and is set to support 500+ manufacturing jobs when operational by 2029. [Genentech]
Always strong on drug manufacturing, North Carolina is among the biggest beneficiaries of biopharma’s reshoring push. In April, AbbVie announced a $1.4-billion, 185-acre drug production facility in Durham County near Research Triangle Park (RTP), expected to employ 734. Roche’s Genentech subsidiary in January expanded to $2 billion its planned investment in its first East Coast manufacturing facility in Holly Springs, NC, which broke ground last year and is set to support 500+ manufacturing jobs when operational by 2029. And in November 2025, Novartis said it will expand Tar Heel State operations into a flagship manufacturing hub by adding capabilities for sterile filling of biologics into syringes and vials at its current Durham site, constructing two new Durham facilities for manufacturing biologics and sterile packaging, and building a new Morrisville, NC, site to produce solid dosage tablets and capsules, including packaging. Morrisville is where Novartis also plans to build a 56,200-square-foot facility focused on API manufacturing for solid dosage tablets, capsules, and RNA therapeutics, a project announced April 30. Manufacturing sites account for most of the combined $24.5 billion in new or expanded facilities with a potential 15,000+ new jobs that life sciences companies have announced statewide since 2021, according to the state-funded North Carolina Biotechnology Center. As for startups, Raleigh-based Slate Medicines launched in February with $130 million in Series A financing to fund development of therapies led by its migraine candidate, the anti-PACAP monoclonal antibody SLTE-1009 licensed from Zhongshan, China-based DartsBio Pharmaceuticals, and set to start Phase I trials in mid-2026.
The Tar Heel State climbed to fourth in VC ($1.6 billion in 2025, $276.8 million in Q1 2026, both according to the state-funded North Carolina Biotechnology Center). But North Carolina showed consistency on the other criteria, ranking seventh in NIH funding (2,248 awards totaling $1.589 billion) and lab space (18.6 million square feet, according to JLL), and eighth in jobs (76,000, says the Center) and patents (5,992 families).
8. Los Angeles / Orange County, CA
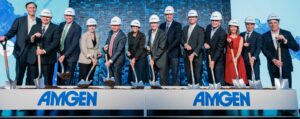
Amgen executives mark the groundbreaking for the biotech giant’s $600 million center for science and innovation being built within its Thousand Oaks, CA, headquarters campus, set to integrate Research & Development and Process Development teams to smoothen the transition from drug discovery to commercial manufacturing. [Amgen]
The region’s biopharma anchor Amgen broke ground last fall on a $600-million center for science and innovation being built within its Thousand Oaks, CA, headquarters campus, set to integrate research & development and process development teams to smooth the transition from drug discovery to commercial manufacturing. “With the first shovel in the ground, we’re reaffirming something essential: We discover here, we manufacture here, we deliver for patients from Thousand Oaks to all around the world,” Amgen chairman and CEO Robert A. Bradway said. Regional industry group BioscienceLA CEO Stephanie Hsieh recently acknowledged the region’s fragmentation as a challenge—from 88 cities in LA County alone, to the numerous county, city, and private agencies focused on growing the bioindustry— while citing strengths such as corporate anchors Amgen, Takeda Pharmaceutical, and Gilead Sciences-owned Kite Pharma, plus institutions like USC, UCLA, Cedars-Sinai, and City of Hope.
California signaled interest in growing the region’s biopharma industry last August when the state-funded California Jobs First Regional Investment Initiative awarded $23.92 million to a coalition led by Los Angeles County’s Department of Economic Opportunity (DEO) toward four programs intended to create 10,000 jobs by 2030. Most of the money ($19 million) was approved for a DEO revolving loan fund to support startups, especially those looking to graduate from the Larta Institute’s commercialization and capital access accelerator into lab space within Los Angeles County. Larta was awarded $3.3 million to expand its Heal.LA Bioscience & Healthcare Accelerator and assist small startups via its Larta Impact Fund, a revolving loan fund.
Los Angeles/ Orange County would still lead the nation in jobs, based on a year-old BIOCOM California tally of 155,571, which also includes San Bernardino and Ventura counties; figures run as low as 116,000, compiled last year for the four counties plus Riverside and Santa Barbara counties (regional industry group SoCalBio). The region finished seventh in patents (7,211 families), eighth in lab space (11.7 million square feet, according to JLL), and 10th in both NIH funding (1,911 awards totaling $1.243 billion) and VC ($500 million in 2025, zero in Q1 2026, according to PitchBook).
9. Chicagoland
AbbVie plans to build two new active pharmaceutical ingredient (API) manufacturing facilities totaling $380 million at its campus in North Chicago, IL, where the biopharma giant is headquartered. [AbbVie]
At least one developer has pivoted to a large non-biotech tenant to help fill a Chicago campus once envisioned as a life-sciences mecca: Trammell Crow in March inked a $100-million, 169,860-square-foot lease with candy/chocolate giant Mars to base 600 jobs at 400 North Aberdeen Street within the Fulton Market campus. Other biotech spaces are in the works: In North Chicago, Rosalind Franklin University of Medicine and Science plans to nearly double the size of its Helix 51 biomedical incubator to just under 13,000 square feet by adding 6,000 square feet of new lab and office space, citing growing demand from early-stage biotechs. The expansion is expected to create space for up to 10 additional companies. Also in North Chicago, home-grown AbbVie announced plans to build two new API manufacturing facilities totaling $380 million at its campus in the Chicago suburb. The facilities—designed to support production of next-generation neuroscience and obesity treatments—are set to be fully operational in 2029. However, AbbVie opted to build its planned $1.4-billion biomanufacturing campus not in North Chicago but 821 miles southeast in Durham, NC. Across Illinois, biotech stakeholders have applauded Gov. J.B. Pritzker (D) for proposing to sweeten the state’s Research & Development Tax Credit program by allowing companies to transfer their credits for cash. “This is a transformative step for our startup and growth-stage ecosystem,” stated John Conrad, president and CEO of the Illinois Biotechnology Innovation Organization (iBIO). Pritzker is seeking a third term in November vs. Darren Bailey (R).
The Windy City and vicinity rank sixth in both NIH funding (2,658 awards totaling $1.607 billion) and jobs (94,000, according to statewide industry group Illinois Biotechnology Innovation Organization or iBIO). The region places ninth in patents (5,569 families) and VC ($917.677 million in 2025, says iBIO, zero in Q1 2026,
10. Seattle
AGC Biologics, a global CDMO, expanded its regional research footprint last fall by signing a 37,575-square-foot lease at Element Research Center in Bothell, WA. [AGC Biologics]
Seattle and the Greater Puget Sound’s strong base of academic and other nonprofit research institutions helped the region achieve consecutive years of Nobel laureates: Mary E. Brunkow, PhD, of the Institute for Systems Biology in Seattle co-won the 2025 prize in Physiology or Medicine a year after David Baker, PhD, director of the Institute for Protein Design at University of Washington (UW), co-won the 2024 prize in Chemistry. A UW spinout, Seattle-based 3D tissue model developer Curi Bio, closed in December on a $10-million Series B financing led by South Korean contract research organization DreamCIS. In April, Achieve Life Sciences (based in Seattle and Vancouver, BC) announced an up-to-$354 million private placement whose purposes include funding a Phase III trial and future commercialization of e-cigarette cessation candidate cytisinicline, while Athira Pharma landed up to $236 million in conjunction with acquiring exclusive rights from Sermonix Pharmaceuticals to the Phase III metastatic breast cancer candidate lasofoxifene. AGC Biologics, a global CDMO, expanded its regional research footprint last fall by signing a 37,575-square-foot lease at Element Research Center in Bothell, WA. However, Astellas Pharma told Washington state officials in April it will shutter the Seattle site of its Universal Cells subsidiary by 2028, with 50 employees to be impacted via layoffs or transfers to South San Francisco, CA, or Westborough, MA.
Seattle and its suburbs placed highest at eighth in both NIH funding (eighth with 1,892 awards totaling $1.572 billion) and VC ($1.06 billion in 2025, zero in Q1 2026, according to industry group Life Science Washington). The region was ninth in lab space (11.46 million square feet, according to regional real estate firm Flinn Ferguson Cresa) and 10th in both jobs (48,765 according to Life Science Washington) and patents (5,416 families).
Erik Terjesen Managing Director Silicon Foundry, a Kearney Company
Clinical development has become the most resource-intensive stage of drug innovation. Across the industry, clinical trials consume 60–70% of total R&D spending, a proportion that continues to rise as trials grow more complex, more data-heavy, and more operationally demanding. The irony is that while science has advanced dramatically, the underlying model for running trials still reflects assumptions from a pre-digital era. The result is an ecosystem in which timelines stretch, costs multiply, and meaningful efficiency gains remain elusive.
AI has reached a level of maturity capable of reshaping this landscape, but its potential remains constrained by a fundamental issue the industry has been slow to confront. The data used to power these systems was never designed with AI in mind. In fact, the true crisis in clinical development today is structural and deeply rooted in how trial data is organized, contextualized, and interpreted.
Why trial models are failing
Clinical trials were built for physical sites, paper workflows, and slow-moving systems. Modern trials look nothing like that. They are distributed, data-heavy, biomarker-driven, and increasingly adaptive, yet they still run on infrastructure designed for a simpler era.
For years, clinical operations have been organized around sites and checklists rather than continuous insight. Data moves in bursts, workflows remain fragmented, and systems rarely talk to one another. Precision medicine expanded what trials could ask of data, but the way trials actually operate has barely evolved.
The problem isn’t only speed or scale. It’s also the quiet erosion of efficiency in places trial plans rarely account for. Across the industry, leaders describe a growing layer of “invisible waste”: repeated handoffs, duplicative manual work, incompatible data structures, and everyday operational friction that steadily stretches timelines and drives up costs, even though it seldom appears in formal project plans.
AI changes the equation, but only if trial data can support it.
Why AI stumbles in pharma
There is no shortage of AI talent, tools, or ambition in the life sciences sector. What is scarce is data that AI can meaningfully learn from. Most early AI-for-clinical-trials initiatives failed not because the models were immature, but because the data they were fed was not curated with clinical intent.
Models trained on large public corpora can identify patterns, but they lack clinical judgment. If the data is unstructured, inconsistently labeled, or lacks contextual metadata, the model will draw the wrong conclusions with absolute confidence. The well-known “ruler problem”—in which an AI system learned to detect malignant skin lesions based on the presence of a ruler beside the lesion—illustrates how easily models latch onto irrelevant signals.
2. Pharma’s internal data is both rich and unusable.
Organizations hold decades of trial data, but these assets are rarely AI-ready. Different study teams, CROs, and geographies used different standards. Biomarker and imaging data are often stored in systems that cannot communicate with EDC or safety platforms. And clinical notes, PDFs, and unstructured documents require interpretation that models cannot perform without curated training sets.
AI amplifies the quality of the data it is given. If the input is clinically inconsistent, overgeneralized, or disconnected from the trial context, the outputs will be clinically meaningless.
Recognizing this, many pharmas are now investing heavily in curated internal datasets, governance frameworks, and senior AI leadership, often in the form of newly created chief AI officer roles. These leaders are tasked with not just deploying tools, but rebuilding the data infrastructure from which future AI insights will emerge.
The new AI toolkit for clinical trials
Once the data foundation is strong, AI becomes a force multiplier across the entire trial lifecycle. Several categories show particularly high near-term impact potential.
Clinical-grade language models: Purpose-built models that ingest curated internal datasets can help draft protocols, refine eligibility criteria, flag operational risks, and interpret historical trial performance. Unlike general-purpose systems, these models are tuned to reason the way experienced clinical scientists do.
Multimodal AI for patient stratification and endpoint optimization: Integrating imaging, labs, digital biomarkers, and historical trial outcomes enables more precise cohort selection and improves the likelihood of detecting true therapeutic effect. These tools help convert today’s complex data streams into actionable insights.
Synthetic and hybrid control arms: While still emerging, these approaches reduce dependence on large traditional control cohorts by incorporating real-world evidence and model-generated comparators when appropriate. The result is faster recruitment and more efficient statistical design.
AI agents for operations: Operational agents can triage site queries, assist with eligibility adjudication, coordinate scheduling, and draft routine documentation. They are particularly helpful in reducing the administrative burden that slows trial execution.
The most underestimated category, and the one with the most long-term potential, is clinical-driven AI, where the model is trained to interpret clinical data the way a researcher with a PhD or a clinician would. This approach addresses the core issue of context, which is essential for decision-making in regulated environments.
From site-centric to data-centric trials
Trials are gradually evolving away from rigid site-based infrastructure and toward data-centric execution. AI accelerates this shift by enabling continuous monitoring, adaptive decision-making, and greater representation across diverse populations. The next phase of this transition requires progress in several areas:
Reliable digital biomarkers collected via wearables and sensors that feed directly into the trial data ecosystem.
Real-world evidence integration that allows trial designs to incorporate external data while maintaining regulatory rigor.
Improved cohort diversity, supported by AI-driven recruitment models that identify and engage underrepresented populations.
Always-on trial oversight, where adaptive protocols adjust based on real-time data rather than periodic interim reviews.
As these elements mature, trials will resemble dynamic learning systems rather than static sequences of predefined events.
Pharma cannot do this alone
The clinical-trial innovation ecosystem is now incredibly fragmented. A myriad of startups, many founded within the last five years, are attempting to solve different slices of the trial process. Some focus on recruitment; others on protocol simulation, operational automation, predictive enrollment, or digital biomarker analysis.
This fragmentation creates noise but also opportunity. The organizations that succeed will be those that adopt a hybrid strategy, in which internal data expertise is paired with carefully selected external partners. Evaluating early-stage companies requires disciplined technical assessment and an understanding of which partners can meet enterprise requirements in a regulated environment.
Pharma organizations also face a structural talent challenge. The best AI engineers often gravitate toward startups rather than large enterprises. This dynamic reinforces the need for partnership models that combine internal governance with external innovation rather than relying exclusively on one or the other.
What AI can (and cannot) fix
While AI can dramatically shorten timelines and improve decision-making, it is not a cure-all. It will not rescue a flawed trial design, replace human oversight, or eliminate the need for regulatory rigor. What it can do is accelerate the work around those elements, optimizing how protocols are developed, how patients are selected, how data is interpreted, and how milestones are achieved. The organizations that reap the greatest benefit will be those with disciplined data stewardship and a willingness to rethink long-held operational assumptions.
Erik Terjesen is the managing director at Silicon Foundry, a Kearney Company
Researchers are digging deeper into biology’s complexity. In preclinical research, the traditional in vivo models are simply not enough to fuel the engine with the relevant translational data needed to progress successfully to the clinic.
As research needs evolve in immunology and immune-oncology—as focus on neuroscience increases and metabolic drugs such as GLP-1-based therapeutics become more prevalent—in vivo model suppliers are being requested to up the game on new platforms. In response, these suppliers are expanding their humanization platforms while developing advanced models that can be used to study complex and overlapping disease biology.
Regulatory factors also affect this market. The continued focus on the reduction of the use of animals by U.S. and European regulatory authorities has further opened the door to new approach methodologies (NAMs). NAMs are not new. Organ-on-chip or microphysiological systems, organoids, and iPSCs have been available for years. Finally, these systems are entering the limelight. Although the NAM market still requires more standardization across platforms, these systems are starting to impact preclinical research.
Building translational engines
The Jackson Laboratory (JAX) recently launched its latest humanized model, the NSG®-SGM3-IL15-MHC I/II DKO (S15-DKO). The S15-DKO represents their latest advancement in generating PBMC-humanized mice, supporting broad engraftment of immune cell subtypes such as CD4+ and CD8+ T cells, CD33+ myeloid cells, and CD16+/CD56+ natural killer (NK) cells. The knockout of the murine MHC Class I/II receptors delays the onset of Graft vs. Host Disease (GvHD).
S15-DKO model is JAX’s latest advancement in generating PBMC-humanized mice, supporting broad engraftment of immune cell subtypes. The knockout of the murine MHC Class I/II receptors delays the onset of Graft vs. Host Disease (GvHD). [The Jackson Laboratory]
The model also supports the engraftment of rare immune cell subsets, including gd T cells and CD19+/CD38+ B cells that retain the memory state of the donor PBMCs.
Another advanced model for CD34+ hematopoietic stem cell (HSC) humanization, the NSG-FLT3-IL15 mouse generates a cellular-diverse human immune system encompassing myeloid cells, mature NK cells, functional dendritic cells, and T cells.
Both models are available in naïve strains, or off-the-shelf pre-characterized PBMC- and HSC-engraftment, along with full preclinical services tailored to immuno-oncology and autoimmune drug discovery.
“With the FDA’s renewed focus on reducing reliance on non-human primates in biologic development, demand for validated, translational preclinical models has never been higher,” said Luke Dimasi, senior director, JAX.
The genetically humanized FcRn platform and the newly expanded Tg32 hALB mouse address this need. Lacking murine Fcgrt and albumin while expressing their human counterparts, the Tg32 hALB is the first model for studying the pharmacokinetics and pharmacodynamics of human albumin therapeutics, as well as human IgG and Fc-domain-based biologics. Preclinical mAb testing services are available.
“Our offering extends beyond the vivarium,” Dimasi emphasized. JAX’s iPSC repository continues to grow with engineered lines carrying disease-relevant mutations linked to Alzheimer’s, Parkinson’s, ALS, and frontotemporal dementia. In 2025, JAX added HALO-tagged and TET-inducible lines to the collection. The acquisition and integration of the New York Stem Cell Foundation (NYSCF) brings complementary patient-derived iPSCs to the portfolio.
“As the field moves towards new approach methodologies (NAMs), we are evolving alongside it,” Dimasi pointed out. “Our in vivo mouse capabilities give us decades of deeply validated biological context. We are now layering human iPSCs and AI-computational phenotyping on top of that foundation to build a convergent translational engine that no single approach could deliver alone.”
Developing relevant models
According to Jason Rashkow, PhD, product manager for research models, Charles River Laboratories, the company’s comprehensive collection of spontaneously developing rat models spans metabolic disease, diabetes, hypertension, and heart failure, providing strong translational relevance across cardiometabolic indications.
Custom diet preconditioning services allow researchers to tailor disease progression to specific study objectives through strategic model selection and diet design. Standardized preconditioning offerings are planned. “This approach will accelerate study initiation, giving researchers faster access to these metabolic disease models,” said Rashkow.
The increasing prevalence of GLP-1-based therapeutics and next-generation incretin and poly-agonist therapies expanding into cardiometabolic indications such as heart failure with preserved ejection fraction (HFpEF) is accelerating demand for advanced disease models. The combination of established disease models, standardized preconditioning approaches, and custom solutions reflects the complexity of modern metabolic drug development.
In addition, optimization of the generation of CD34+ HSC-humanized mice continues. These models, developed on the severely immunodeficient NCG strain, support research in immuno-oncology, autoimmune disease, vaccine research, and related fields.
As immuno-oncology research needs shift, so does the need for models that enable the study of NK cell-based therapies, tumor microenvironment reprogramming, and cancer vaccines. “Although variant NCG models expressing human cytokines or HLA transgenes begin to meet these needs, transgenes can influence humanization requirements,” Rashkow noted.
To counteract this, the company expanded access to a peripheral blood mononuclear cell (PBMC) engrafted NCG variant strain carrying a double knockout for murine MHC class I and class II, which significantly delays the onset of GvHD, allowing for longer-term studies in the context of mature T cells.
To better support researchers studying HLA-A2-restricted immune responses in vivo, humanization optimization of a NCG variant expressing human HLA-A*02:01 was completed. Further development of the humanization protocols for other variant strains will support next-generation immunotherapy discovery and translational research.
Lastly, the expanded aged C57BL/6 mouse offerings support researchers investigating age-related disease. As a licensed distributor of JAX® Mice to researchers in Europe and Asia, Charles River Europe can now provide aged C57BL/6J mice up to 90 weeks of age. In North America, Charles River offers aged C57BL/6N mice up to 77+ weeks of age.
Improving translational fidelity
“Improved translational fidelity, increased demand for study-ready systems that better align with clinical endpoints, and the need to model complex and overlapping disease biology are driving model development,” related Michael Seiler, PhD, vice president of portfolio management, Taconic Biosciences.
Complex modalities such as checkpoint inhibitors and engineered cell therapies require more complete immune system function and deeper phenotyping. Expansion of the FcResolv® NOG portfolio and huSelect services reduces murine immune interference and donor variability. Advanced flow cytometry panels support deeper, standardized
immune profiling.
With the goal of improving translation relevance, Taconic develops in vivo models that reflect complex and overlapping disease biology in immunology, immuno-oncology, neurobiology, and cardiometabolic indications. [Taconic Biosciences]
Planned launches include platforms and models designed to support immuno-oncology, biologics, engineered cell therapies, infectious disease, and autoimmune research, with a focus on more complete and functional human immune system biology. Gene and protein analysis services are available.
In neuroscience, the shift is toward better alignment with clinical disease biology, particularly in Alzheimer’s disease and neuroinflammation, along with increased focus on blood-brain barrier (BBB) biology and CNS delivery. Parkinson’s disease model offerings include aSyn KI/KO, PINK1 KO, and LRRK2 KO rat models.
Future models include BBB-focused platforms such as TFRC and CD98, ARTE10 crosses with BBB models, and neuroimmunology-focused NOG variants, including IL-34 and TREM2-related models.
The rapid growth of obesity therapeutics, including GLP-1 and next-generation incretin approaches, is accelerating demand for more predictive metabolic and liver models in cardiometabolic disease. A range of models are aimed at obesity, MASH, cardiovascular disease, and DMPK applications.
Taconic is expanding its capabilities in transgene characterization, CRISPR off-target analysis, and tiered Custom Model Generation Solutions. The acquisition of TransCure bioServices significantly bolsters support of integrated in vivo study services, particularly in humanized immune system and immuno-oncology research. “We now offer a more seamless, end-to-end solution from model selection through study execution and data generation,” said Seiler.
“We continue to evolve toward integrated solutions rather than standalone models. This includes expanded CMS and CMGS capabilities, humanization-as-a-service, deeper phenotyping and multiomic analysis, and partner-enabled data generation,” Seiler added.
Importantly, the move toward integrating in vivo models with complementary technologies such as organoids, iPSCs, and AI-enabled analysis will influence how models are developed and deployed within research workflows.
Standardizing NAMs
The field is clearly shifting toward ready-to-use biology, producing a strong demand for standardized NAM platforms and services that deliver consistent, high-quality results. To facilitate scientists, MIMETAS continues to develop robust OrganoReady® models and advanced services, including immune-competent and vascularized systems across multiple organs.
“Last year, we strengthened our fee-for-service capabilities and advanced several models to deliver high-quality biology in a consistent, scalable way,” said Paul Vulto, PhD, co-CEO and co-founder, MIMETAS. “We made strong progress in our kidney tubuloid research program, CAR T-related applications, and a BBB model under unidirectional flow.”
The novel human distal nephron-on-chip model in the OrganoPlate® replicates physiologic sodium and water transport using primary human kidney cells. This three-dimensional microfluidic platform, as detailed in Kidney360, serves as a high-throughput tool for functional drug screening and investigating distal nephron physiology and disease.1
A polarized kidney tubuloid in an OrganoPlate chip showcases apical and basolateral access. Immunofluorescence 3D reconstruction demonstrates tubule polarization and barrier formation: blue, DNA; red, acetylated tubulin; and green, Na /KATPase. [MIMETAS]
In addition, a three-dimensional BBB microvasculature model developed on the OrganoPlate Graft 48 UniFlow was evaluated in a recent Fluids Barriers CNS publication. Tri-cultures of endothelial cells, pericytes, and astrocytes were used to demonstrate that this pump-free, unidirectional perfused, three-dimensional BBB model outperformed simpler systems on vascular architecture and barrier function. Its high-throughput nature renders the model suitable for studies of BBB function in health, disease, and therapeutic development.2
This year, the company’s UniFlow technology will be offered for in-lab use, enabling customers to create a stable, perfusable vascularized bed for endothelial tissues. New OrganoServices for gastrointestinal toxicity (GI tox) and drug-induced vascular injury (DIVI), alongside a multi-donor expansion of the OrganoReady Colon Organoid product, are also planned.
A major trend in NAMs is the increased need for standardization and regulatory alignment across the field. With initiatives like IAMPS (Industry Alliance for MicroPhysiological Systems), of which MIMETAS is a founding member, industry innovators will work together to advance regulatory acceptance.
The space is evolving quickly, but Vulto emphasized that their focus remains unchanged: building robust human models that help researchers make better decisions.
Improving organoid access
“Organoids are part of a broader innovation focus to help researchers work with more predictive models, more advanced tools, and more connected workflows across the path from discovery to development,” commented Heather Hargett, PhD, head of cell biology reagents franchise at MilliporeSigma, the U.S. and Canada Life Science business of Merck KGaA, Darmstadt, Germany.
The regulatory landscape is becoming increasingly favorable to NAMs. In March 2026, the FDA issued a draft guidance to establish clear validation principles for NAMs, including organoids and in silico (or AI) models, when submitted in support of drug applications.
Phasing out animal use for research and regulatory purposes is also supported by the European Commission’s Roadmap Towards Phasing Out Animal Testing for Chemical Safety Assessments.
Patient-derived organoids (PDOs) retain individual genetic and phenotypic characteristics, enabling drug response testing across diverse patient backgrounds and disease subtypes. The image shows immunocytochemical (ICC) characterization of human colon PDOs that are positive for the colon-specific marker CA II (green), nuclei (blue) and actin (red). [MilliporeSigma, the U.S. and Canada Life Science business of Merck KGaA, Darmstadt, Germany
HUB’s advanced organoid capabilities are now being combined with the company’s cell culture expertise, manufacturing scale, global commercial reach, and broad life science portfolio to make organoids a more practical and scalable tool in drug discovery and translational research.
Key priorities include expanding the validated organoid biobank across additional therapeutic areas, tissues, disease states, and patient backgrounds. “Last October, we announced a strategic partnership with Promega Corporation,” said Hargett. “By combining our organoid expertise with Promega’s advanced reporter technology, we aim to enable high-throughput screening that helps researchers identify safer and more effective drug candidates.”
The case of petosemtamab, developed by Merus, is a notable example of the real-world impact of organoid technology. Petosemtamab’s efficacy was tested using HUB organoids. The EGFR x LGR5 bispecific antibody has received FDA Breakthrough Therapy Designation for use in combination with pembrolizumab for first-line treatment of PD-L1-positive recurrent/metastatic head and neck squamous cell carcinoma (HNSCC). A global Phase III trial is ongoing. Recently, Genmab acquired Merus for approximately $8 billion USD.
Adopting organoid technology is a capital efficiency strategy, according to Hargett. Patient-derived organoids retain individual genetic and phenotypic characteristics, enabling drug response testing across diverse patient backgrounds and disease subtypes. Organoids support a “fail fast” approach by identifying non-viable candidates earlier, reducing costly late-stage clinical trial failures, and allowing companies to redirect resources toward the most promising programs.
References
Bernardi MDL, Dilmen E, Kurek D et al. A Novel Human Distal Tubuloid-on-a-Chip Model for Investigating Sodium and Water Transport Mechanisms. Kidney360. 2025 Nov 1;6(11):1981-1993. doi: 10.34067/KID.0000000992.
Admiraal J, Emeh PO, Bokkers M et al. Building the blood-brain barrier: a scalable self-assembling 3D model of the brain microvasculature under unidirectional flow. Fluids Barriers CNS. 2026 Jan 23;23(1):29. doi: 10.1186/s12987-026-00765-x.
Laurence Arnold, PhD Head of R&D Pelago Bioscience
We’ve never had more data in drug discovery. Yet despite this explosion in capability, our industry’s most fundamental challenge remains stubbornly intact: making confident early decisions about which drug programs deserve billion-dollar investments, and which should be shelved.
It costs two to three billion dollars to bring a drug to market, with a 90% failure rate, often higher. These numbers mask something more troubling. We’re not just failing because biology is hard; we’re failing because the mountains of data we’re generating aren’t giving us what we actually need at decision points that matter.
In my view, we don’t have a data volume problem—we have a data relevance problem.
Biological activity is not relevance
Traditional drug discovery relies on a “dissect and build” approach: isolate one variable, measure it in a controlled environment, then extrapolate. It’s disciplined. It’s reproducible. And it has delivered important medicines.
But the persistently high failure rate in drug development tells us we’re reaching the limits of this approach. In reality, biology operates through cascading networks, feedback loops, and context-dependent equilibria. These are dynamic biological systems where cause and effect rarely follow straight lines.
We’ve successfully drugged only about 650 of 20,000 potentially druggable proteins. Not because scientists lack talent, but because for most targets, we don’t have robust ways to measure what matters—the initiating molecular event in a biologically relevant context.
We’re good at measuring activity. What we struggle with is measuring relevance.
An assay telling you a compound binds to your target protein is useful, but does it bind in living cells? In the disease context that matters? With the pharmacokinetics to reach patients? A compound brilliant in a purified enzyme assay might never reach its target in cells, or it might hit off-targets producing effects through entirely different mechanisms.
The result? Ever-expanding data sets that still don’t answer the critical question in modern drug discovery: Are we making the right decision?
The cost of borrowed confidence
There’s a human dimension here that rarely makes it into industry discussions. Despite what is often repeated in drug discovery circles, scientists in R&D are rewarded for being right, not for being bold.
Most scientists think in terms of “future hindsight”: will we look back and realize we missed something obvious? The responsibility isn’t to push programs forward at all costs. It’s to execute each step well, knowing that most will fail. Success stories often appear bold in retrospect. In practice, they are usually built on careful, incremental decisions that gradually improve the odds.
So, teams do their jobs with discipline and rigor. They hit milestones, generate data, and advance programs. Everyone knows 90% of projects will fail, but this one has shown activity in the assay, has a plausible mechanism, and has momentum. The data might not be perfect, but it’s good enough to keep going.
Until it isn’t. And the failure comes late, after years of effort and hundreds of millions spent.
Of course, failure is how science advances. But many of these failures were avoidable earlier. Hard-working teams just didn’t have data that would let them make the call with confidence when it mattered most, before massive resources were committed.
What decision-ready evidence looks like
The best experiment isn’t always the one that moves your program forward—it’s the one that tells you when to stop.
Think of it as taking a stepladder to look over a thick hedge rather than hacking through it with an axe. You might not learn everything about what’s inside it, but you’ll know much faster whether there’s anything worth pursuing on the other side.
The pharmaceutical industry has been built on a model of going through the hedge, but the resource cost and timelines are increasingly untenable. So, what would an alternative, evidence-driven discovery model look like?
Evidence-driven discovery requires a hierarchy of questions. Before optimizing potency or selectivity, can you prove that engaging this target in this context produces therapeutically relevant effects? Not in an abstract system, but in actual disease biology.
This is about front-loading proof of concept before investing in optimization. Measure the initiating molecular interaction early, free from tags or unnatural expression control, in cells and tissues that approximate disease.
It also requires new frameworks for proof of target engagement. We’re seeing this with technologies that measure binding in native cellular contexts, patient-derived models, and translational designs that test hypotheses much earlier in preclinical development. The goal isn’t replacing traditional assays, but knowing which programs deserve that investment.
Ultimately, the win comes from making the right decision at each stage, even when that decision is to stop.
The path forward
Successful programs will establish coherent lines of evidence from initial target engagement through preclinical models to human proof of concept—and they will do it fast enough to fail early when evidence doesn’t align.
This means rigorously testing hypotheses in the real biological context of disease before perfecting molecules or committing billions of dollars.
Some will argue this is unrealistic—that you need optimized compounds, and that shortcuts lead to false negatives killing promising programs. These concerns aren’t wrong; they’re just insufficient when the old model demonstrably isn’t working.
The real question is whether the risk of earlier translational testing exceeds spending nine years and a billion dollars on a target that was never going to work.
Making the call with confidence
Here’s what I tell my team: Your job isn’t to get a drug to the clinic. Your job is to do each step exceptionally well, building evidence you can defend. Because if we’re systematic about gathering the right evidence early, and if we’re honest about what the data is—and isn’t—telling us, the statistics start working in our favor.
The industry is moving toward evidence-first approaches—technologies validating targets in relevant contexts, translational frameworks testing hypotheses earlier, and computational tools trained on quality data.
But all this data is just noise until it answers the question keeping many of us up at night: Can I make this call with confidence, or am I crossing my fingers and hoping?
We won’t solve the 90% failure rate entirely. Biology is too complex. But we can close the confidence gap by using the right data, at the right time, to answer the key question: Should we keep going?
And sometimes—often, even—the most valuable answer will be no.
Laurence Arnold, PhD, is the Head of R&D at Pelago Bioscience.


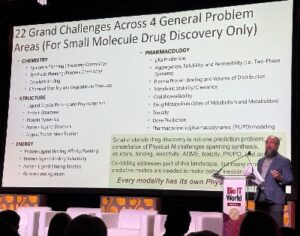
 . XRx-026 is being developed for patients with allopurinol intolerant gout.